
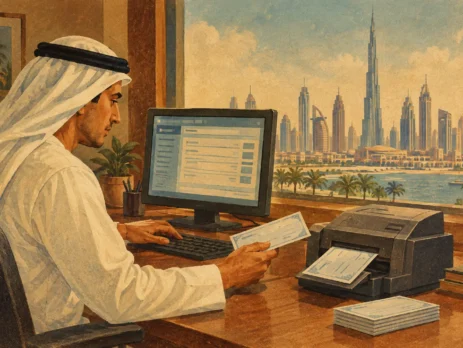
CHQ Printing Software for Dubai Businesses
A finance team should not have to correct payee alignment, amount fields, or signature spacing after a check has already reached the printer. The right chq printing software for Dubai turns check issuance into a controlled business process, with approved templates, validated payment data, user permissions, and a traceable print history.
For companies operating in Dubai, the requirement is more specific than simply printing an amount on a blank check. Bank stationery formats differ, finance teams may process AED and foreign-currency payments, and approval controls must align with internal accounting policies. The software, printer, workstation, and network environment all need to work together without introducing avoidable operational risk.
What CHQ Printing Software Must Handle
A suitable application should support the exact check format issued by the organization’s bank. This includes the placement of the date, payee name, numeric amount, written amount, account number, and any preprinted security elements. A generic template may appear acceptable on screen but still fail when used with bank-issued stationery. Test printing on the actual check stock is therefore a deployment requirement, not an optional final step.
The application also needs accurate amount-to-words conversion, including AED denomination conventions where required. Small formatting errors can cause manual corrections, delayed payments, or rejected checks. If an organization issues checks from more than one legal entity or bank account, the system should maintain separate templates and account profiles rather than relying on staff to switch settings manually.
Integration is the next consideration. Some businesses need a standalone tool for occasional controlled printing. Others require data to come directly from accounting or ERP platforms, such as SAP, Microsoft Dynamics, Tally, QuickBooks, Oracle, or a custom finance system. The appropriate choice depends on payment volume and process maturity. Direct integration can reduce rekeying, but it requires mapping, testing, access controls, and ongoing support when the accounting environment changes.
Selecting CHQ Printing Software for Dubai Operations
Start with the bank format, not the software brand. Obtain a physical sample of each checkbook or continuous stationery type used by the business. Confirm whether the bank provides an approved layout, coordinate measurements, or specific print restrictions. A solution that supports custom template positioning is often necessary when a company uses different banks or maintains multiple accounts.
Next, define who is allowed to create, approve, and print a check. In smaller organizations, one finance employee may perform several tasks. In higher-control environments, payment preparation, review, approval, and printing should be separated. The software should support role-based permissions where possible and should not allow every user with access to a shared PC to reprint, alter, or void payment records.
A practical selection review should cover these capabilities:
- Custom check templates matched to bank-issued stationery and printer margins.
- Multi-company, multi-bank, and multi-currency payment profiles.
- Import or integration options for accounting and ERP payment data.
- User roles, approval workflows, reprint restrictions, and audit logs.
- Support for voided checks, duplicate prevention, and check number sequencing.
- Exportable reports for reconciliation, audit review, and payment tracking.
Not every organization needs every function. A company printing ten checks per month may prioritize template accuracy and simple reporting. A group with several entities, distributed finance teams, and daily supplier payments should place more weight on approval controls, system integration, and centralized administration.
Template Accuracy Is a Financial Control
Check layouts are often treated as a cosmetic setup task. They are not. Incorrect placement can expose sensitive account data, leave a material amount field unclear, or create a payment document that is difficult for a bank to process. The most reliable implementation uses calibrated printer settings, documented paper orientation, and a signed-off test print for every account template.
Changes must also be controlled. Replacing a printer, moving to a new workstation, updating a driver, or switching check stationery can shift print coordinates. Finance teams should retain the approved configuration and repeat test printing after any material change. This matters particularly with laser printers, where tray selection, scaling settings, and driver defaults can differ across devices.
Accounting Integration Requires Clear Ownership
An integration can improve speed, but it should not blur responsibility for payment authorization. The accounting system should remain the source of payment data, while the printing application should apply the approved template and retain its own print activity record. If a payment is edited after approval, the process should require a new review rather than silently printing the modified value.
Before deployment, confirm how the software handles supplier names with long legal descriptions, special characters, foreign currencies, and invoice references. Also confirm whether it imports only approved payment batches or can pull draft transactions. These details determine whether the system supports the finance process or creates another reconciliation task.
Infrastructure Requirements Behind Reliable Check Printing
CHQ printing is a finance application, but its reliability depends on the supporting endpoint and network design. A dedicated finance workstation is generally easier to secure and support than a shared office computer. It should have a supported operating system, current printer drivers, endpoint protection, controlled local administrator access, and a documented backup approach for templates and configuration files.
Where a network printer is used, assign a stable IP address or DHCP reservation and place the device in the appropriate network segment. Printing may be simple, but an unsecured shared printer can expose payment documents to unauthorized staff. Access to the printer queue should be restricted, and printed checks should not remain unattended in an open output tray.
Organizations with centralized infrastructure may use a print server to manage driver versions, queue permissions, and audit records. This is useful when multiple finance users print from separate locations or when the check printer must be available under a controlled service account. It also reduces the risk of workstation-specific configurations producing different output.
The printer itself should be selected for paper-path reliability, manual feed support where needed, and consistent positioning on check stock. Duplex settings, automatic scaling, toner-saving modes, and document-fit options should be disabled for the relevant print queue. A low-cost office printer can be adequate for limited volume, but it may be a poor fit for high-volume payment operations or specialized continuous stationery.
Security, Auditability, and Business Continuity
A printed check is a payment instrument, so the surrounding controls deserve the same attention given to online banking access. The system should record who created a payment record, who approved it, when it was printed, which check number was used, and whether a reprint occurred. Reprints should require a reason code or supervisory approval, especially where blank signed checks or pre-authorized stationery are involved.
Check stock should be stored securely and counted periodically. Organizations should reconcile used, voided, and unused check numbers against the software report and bank records. This protects against both accidental duplication and intentional misuse. A system that prints correctly but provides no usable audit trail may be acceptable for a very limited process, but it is not appropriate for a controlled finance environment.
Business continuity also matters. If the designated workstation fails on payment day, the organization needs a documented recovery path. That may include a backup device with the approved printer driver, secured copies of templates, tested user access, and a clearly defined authorization process. Backing up the application database alone is not enough if the printer configuration and layout files are stored locally and undocumented.
Implementation Steps That Reduce Rework
A controlled rollout is usually faster than trying to solve formatting and access issues after payment processing begins. Begin by documenting each bank account, check stock type, printer model, payment volume, and user role. Build the initial template using real stationery, then perform test prints with representative payment data, including long payee names and large amounts.
After finance signs off on the output, test the full workflow: import or entry, approval, print, reprint prevention, voiding, reporting, and reconciliation. Include the IT team when printer permissions, endpoint policies, print servers, or network segmentation are involved. This prevents a functional finance application from failing because of a driver policy or blocked print service.
Finally, write a short operating procedure. It should state which printer and tray to use, who approves a batch, how errors are voided, where check stock is stored, and how a failed print is handled. Clear instructions are particularly valuable when finance responsibilities shift between staff or when a company operates multiple entities.
The best CHQ printing deployment is not the one with the longest feature list. It is the one that matches the bank stationery, payment workflow, security policy, and supporting IT environment closely enough that every issued check can be printed, traced, and reconciled with confidence.

I am an enthusiastic tech blogger with 15 years of experience in the technology field. I am passionate about sharing valuable insights and helping people who are interested in technology gain useful and practical information. I am originally from Mumbai, India.



Leave a Reply